Fitting a new set of alloys or upgrading an exhaust might seem like a personal choice, but your insurer may see it differently. Modified car insurance in the UK is largely about making sure the company covering your vehicle knows what it is actually insuring. A change does not need to make the car faster to matter: appearance, security and replacement costs can all affect an insurer’s decision.
What counts as a modification for insurance?
Insurers generally mean a change from the manufacturer’s standard specification. However, definitions vary between policies. Optional equipment fitted by the manufacturer, accessories installed by a dealer and parts added by a previous owner can be treated differently. Do not assume that a change is exempt simply because the vehicle looks almost standard.
Which car modifications should you declare?
Engine and performance changes
ECU remapping, turbocharger upgrades, engine swaps and performance exhausts are obvious examples to discuss with your insurer. Changes to suspension, lowered ride height and upgraded braking systems also deserve attention. They can affect handling, power, repair complexity or the insurer’s assessment of risk, even when the work has been carried out professionally.
Wheels, bodywork and styling
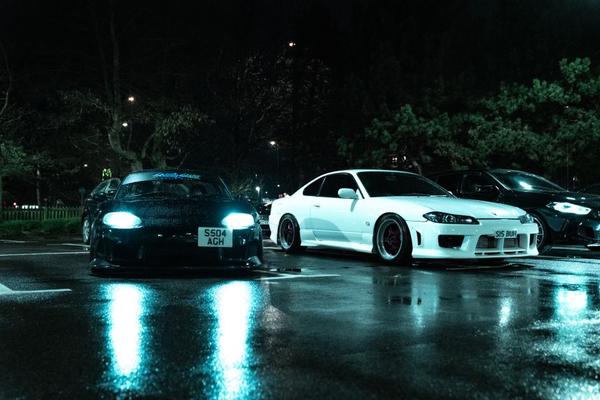
Non-standard alloy wheels, wheel spacers, body kits, spoilers, tinted windows and custom paintwork may also count. A wheel upgrade that looks purely cosmetic can alter replacement costs or theft attractiveness. The Financial Ombudsman Service has highlighted disputes involving undisclosed alloys, demonstrating why drivers should not dismiss visual changes as irrelevant.
Interior, technology and security upgrades
Modified seats, upgraded audio systems, aftermarket lighting and changes to vehicle security can be relevant too. Some insurers may accept certain accessories without an additional charge, while others will want them recorded. Approved immobilisers can sometimes help with premiums, but a security upgrade should still be described accurately rather than assumed to earn a discount.
Why modification disclosure matters for claims
A claim is often when an undisclosed modification comes to light. An assessor might notice non-standard wheels after an accident or an altered engine setup after a theft. The insurer may then investigate what was disclosed, what questions were asked and whether the change would have affected its decision to provide cover.
That does not mean every undeclared accessory automatically makes a policy void. Under the Consumer Insurance (Disclosure and Representations) Act 2012, consumers must take reasonable care not to make a misrepresentation when taking out or varying insurance. Where an insurer establishes a qualifying misrepresentation, available remedies depend on the circumstances, including whether the error was careless or deliberate and what the insurer would have done with accurate information.
Will modifying your car increase your premium?
Possibly, but not always. Insurers may look at increased performance, theft appeal, repair costs and availability of replacement parts. A specialist provider may be comfortable with changes that a standard insurer will not accept. Some modifications can be noted without a premium increase; others can lead to a higher excess, changed terms or refusal to cover the altered vehicle.
For example, imagine your hatchback is insured on standard wheels and you want to fit larger aftermarket alloys costing £900. Ask the insurer before purchasing them whether it will continue cover, whether your premium will change and what happens if the wheels are stolen or damaged. These are three separate questions. Approval to drive the modified car does not necessarily mean the full value of those wheels is insured.
When comparing modified vehicle insurance, check the policy conditions as carefully as the quote. Our guide to comparing car insurance quotes can help you assess price alongside exclusions and excesses, rather than focusing on the cheapest premium alone.
Does aftermarket parts insurance cover the cost of upgrades?
Not automatically. One policy might insure the car with its declared modifications but settle a loss using the value of standard replacement parts. Another may offer an agreed valuation, a stated accessories limit or specialist cover for upgraded components. These differences matter if you have spent substantial money on wheels, audio equipment or performance parts.
Ask how the insurer values the complete vehicle, whether individual aftermarket parts are covered and whether you need receipts, installation records or photographs. Keep in mind that spending £2,000 on modifications does not necessarily increase a car’s market value by £2,000. Our explanation of comprehensive car insurance is also useful when separating protection against damage to your own vehicle from the treatment of optional upgrades.
How to tell your insurer about a change
Contact the insurer before work begins where possible. Describe the modification precisely, including the part, specification, installation date and whether it affects performance or appearance. If the car is already modified, disclose what you know when applying for cover and clarify uncertainties instead of guessing.
Ask for written confirmation of acceptance, the revised premium or excess, and any limits on replacement parts. Check the updated schedule and policy documents after the change is recorded. Save emails, receipts and photographs together; they may help if there is a disagreement about what was declared.
If you bought the car used, examine advertisements, service records and invoices for evidence of earlier modifications. An inspection by a knowledgeable garage can help identify uncertain changes, although it does not replace the insurer’s own decision.
Do you also need to notify DVLA?
Insurance disclosure and vehicle registration are separate responsibilities. DVLA requires changes to V5C details for certain alterations, including vehicle colour, engine, cylinder capacity, fuel type and seating capacity. Some structural changes require supporting evidence. Updating DVLA does not notify your insurer, and notifying your insurer does not update your V5C.
Frequently asked questions
Do I need to declare modifications made by a previous owner?
Tell the insurer about changes you know about, even if you did not install them. If something is uncertain, explain that and ask what information the insurer needs. Whether an omission amounts to a misrepresentation depends on the facts, including what a reasonable customer could have known.
Do cosmetic modifications affect UK car insurance?
They can. Tinting, alloys, spoilers and wraps may affect underwriting or replacement costs. Ask your provider rather than assuming only engine upgrades need declaring.
Can I declare a modification after fitting it?
Contact your insurer immediately, explain when the work was completed and ask whether cover can continue. Do not assume a change is accepted until the insurer confirms the position.
Will my insurer replace upgraded parts after an accident?
Only to the extent your policy provides. Modification disclosure is different from obtaining cover for the full replacement value of aftermarket components.
Final thoughts
The important question is not simply whether your car has been changed, but whether your insurer understands those changes and agrees to cover them. Declare alterations early, confirm the effect on price and claims, and keep the paperwork. For modified car insurance in the UK, that short conversation before fitting a part can be far more valuable than discovering a disagreement after something goes wrong.